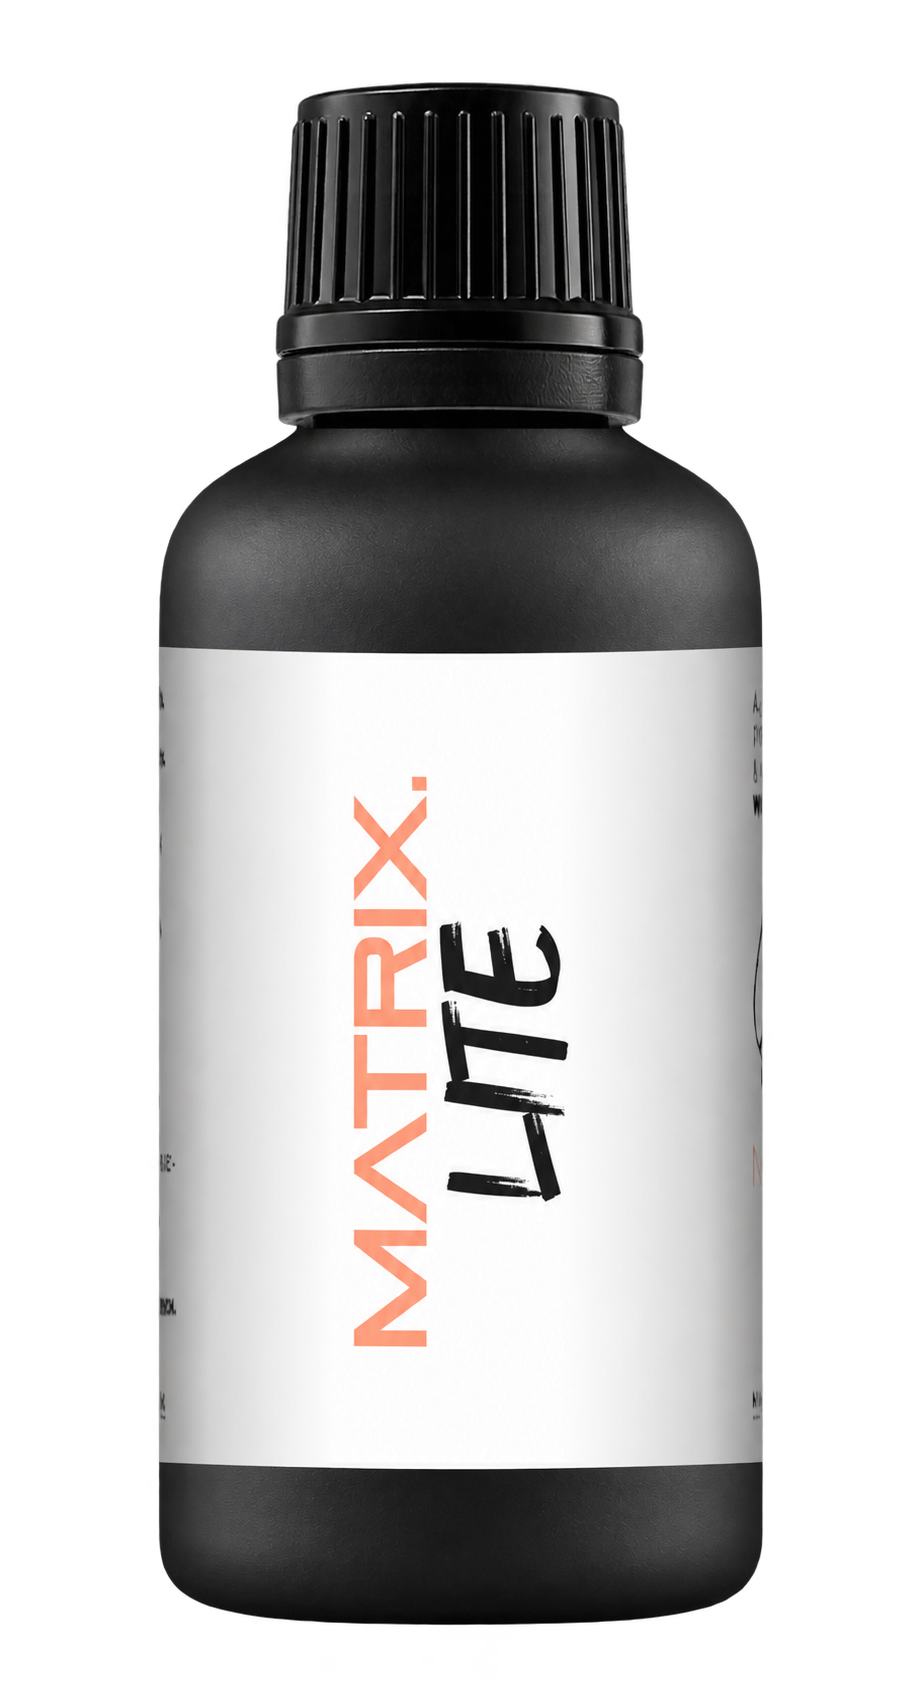
A full polishing range.
From cutting and one-step correction to final finishing.
Specialist chemistry. Expert application.
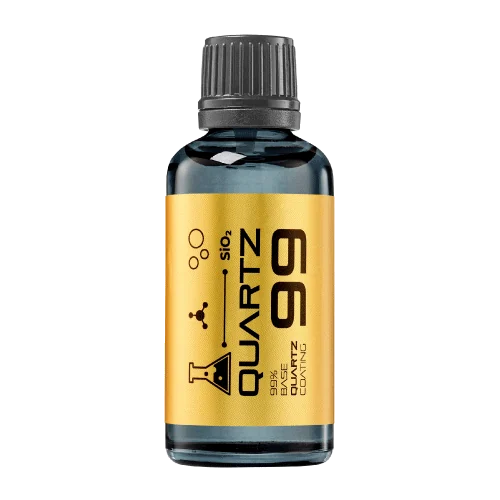 QUARTZ99 / CERAMIC BASE COAT
The foundation of your coating system.
A layerable quartz base coat designed for mechanical protection. Pair it with a suitable top coat to create the final finish.
For application by NANOLAB certified installers only.
Four formulas. Extended working time. Find the coating for your finish.
Explore the BEAST family of ceramic coatings.
Find the coating for each exterior surface.
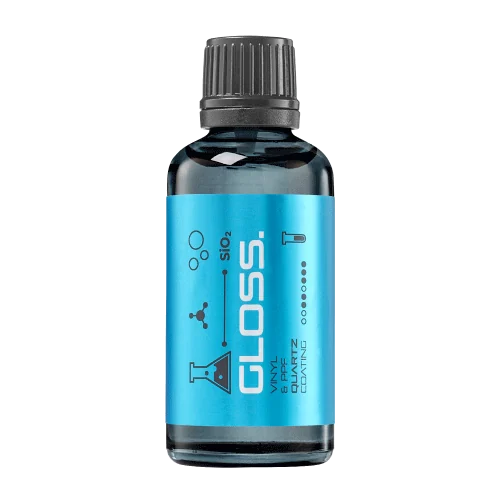 PPF & VINYLGLOSSProtection for glossy films and wraps.Discover
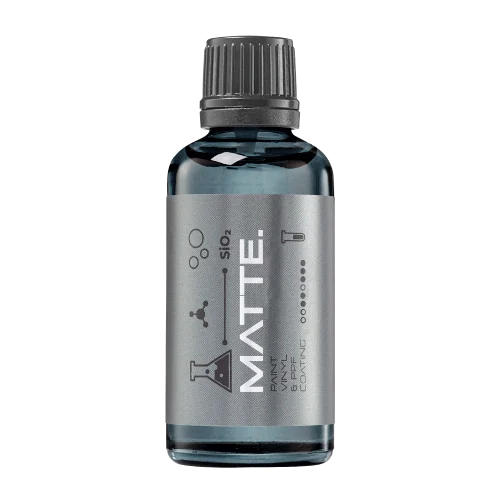 MATTE & SATINMATTEProtection that respects the finish.Discover
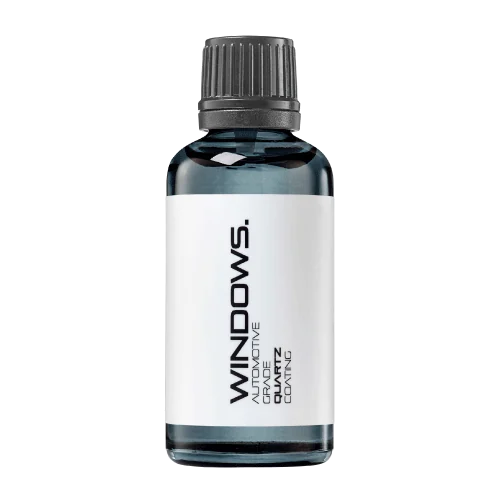 GLASSWINDOWSExplore dedicated glass protection.Discover
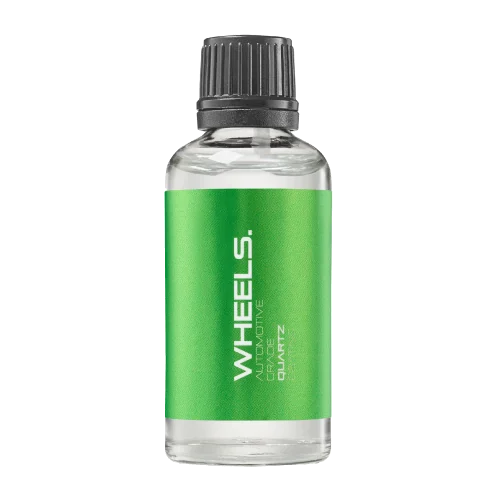 WHEEL PROTECTIONWHEELSA dedicated coating for your wheels.Discover
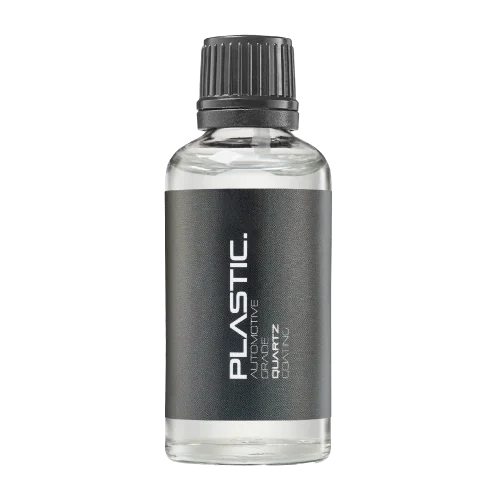 TRIM PROTECTIONPLASTICProtection for plastic surfaces.Discover
Dedicated care for the surfaces inside.
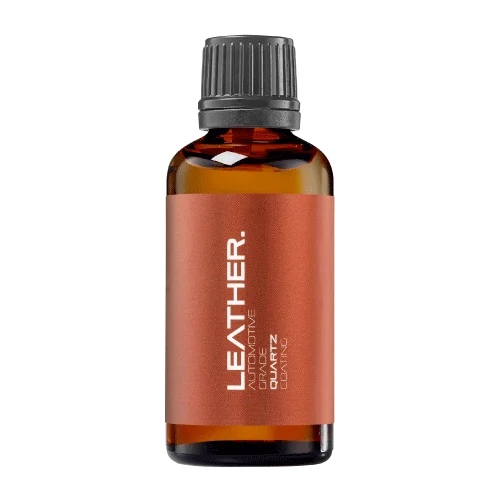 LEATHER SURFACESLEATHERDiscover NANOLAB leather protection.Discover PLASTIC SURFACESPLASTICProtection for interior plastic surfaces.Discover TEXTILE SURFACESFABRICExplore the latest fabric formulation.Discover
Spray protection, maintenance and upcoming wash products.
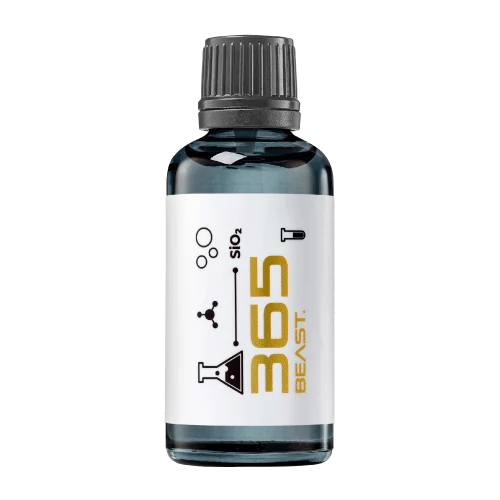 MAINTENANCEBEAST 365Explore the BEAST maintenance range.Discover
Next in washing, cleaning & care.
Ceramic protection for boats and yachts.
An easy-to-apply ceramic coating with an established track record on boats and yachts around the world.
Results vary with surface preparation, exposure and maintenance.
Read 50 MARINE guides →Explore MARINEProtection for the surfaces you live with.
A look at what we’re developing.
From cutting and one-step correction to final finishing.
A wider range for professional vehicle care.
Taking shape alongside BEAST & MATRIX.
Practical guidance for your next coating project.
Explore all guides →
Plan your NANOLAB private label coating range: product briefs, sample evaluation, packaging, pilot installations and customer support.
Higher repeat revenue can come from larger orders, more frequent orders or a different mix of customers. Separate these drivers before deciding which part of a coating programme is working.
Revenue growth does not necessarily mean that more coating units were sold. Price changes and a shift toward different products can raise revenue even when physical volume stays flat or declines.
Returns can relate to sales made in an earlier period. A coating sales review should state whether it measures accounting-period net sales, the outcome of a sales cohort or another defined view.
Inventory turnover should compare a defined cost flow with inventory measured on a compatible basis. Dividing sales revenue by stock cost mixes different quantities and can make the resulting ratio difficult to interpret.
Gross margin return on inventory relates gross margin to average inventory investment over a defined period. It can help compare stock commitments, but only when both quantities use consistent scope and clearly stated definitions.
Sequential discounts apply to changing bases. Two ten-percent discounts normally produce a nineteen-percent reduction from the original price when the second is applied to the already discounted amount.
A lower unit price can still require a larger total cash commitment and more stock. Compare the full order at each available tier rather than selecting the cheapest printed unit price automatically.
Adding coating stock to reach a freight threshold can reduce a delivery charge while increasing the overall order commitment. Calculate both effects before describing the larger basket as a saving.
Finding no defects in a sample does not prove that the entire production population is defect-free. Report the sample size, selection method and inspection criteria alongside the observed result.
Bottles allocated to approved sampling or demonstrations should remain distinguishable from ordinary saleable stock. Otherwise, an availability report can promise units that the business has already committed to another purpose.
A conditional rebate is not the same as a discount already earned on an order. Keep the qualifying conditions visible when using a rebate assumption in a coating purchasing forecast.
A multi-product coating order can share packaging, handling and delivery costs. Allocate those costs consistently for product analysis while ensuring the whole-order calculation includes each cost only once.