A full polishing range.
From cutting and one-step correction to final finishing.
Specialist chemistry. Expert application.
 QUARTZ99 / CERAMIC BASE COAT
The foundation of your coating system.
A layerable quartz base coat designed for mechanical protection. Pair it with a suitable top coat to create the final finish.
For application by NANOLAB certified installers only.
Four formulas. Extended working time. Find the coating for your finish.
Explore the BEAST family of ceramic coatings.
Find the coating for each exterior surface.
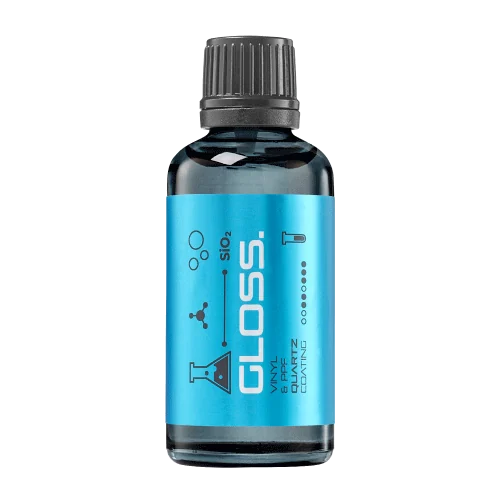 PPF & VINYLGLOSSProtection for glossy films and wraps.Discover
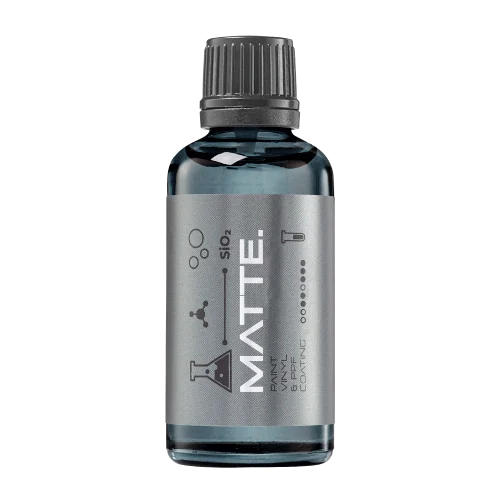 MATTE & SATINMATTEProtection that respects the finish.Discover
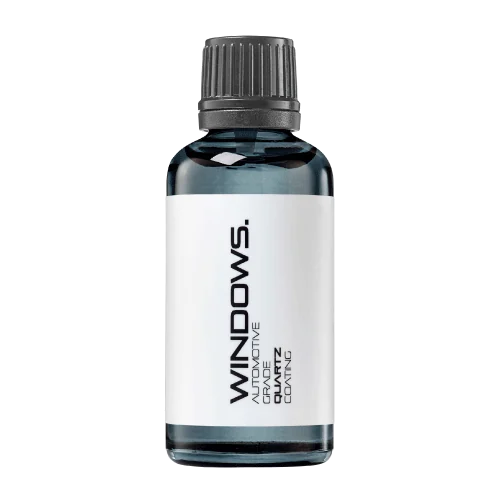 GLASSWINDOWSExplore dedicated glass protection.Discover
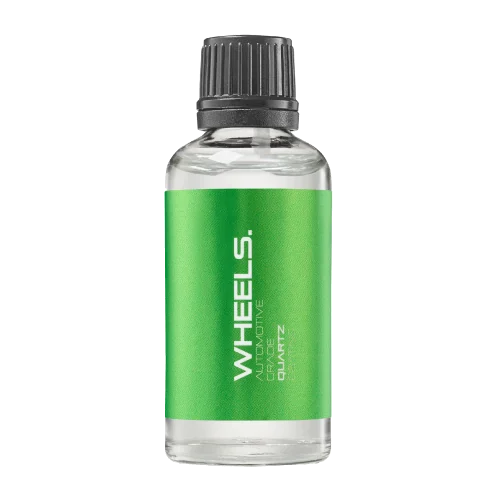 WHEEL PROTECTIONWHEELSA dedicated coating for your wheels.Discover
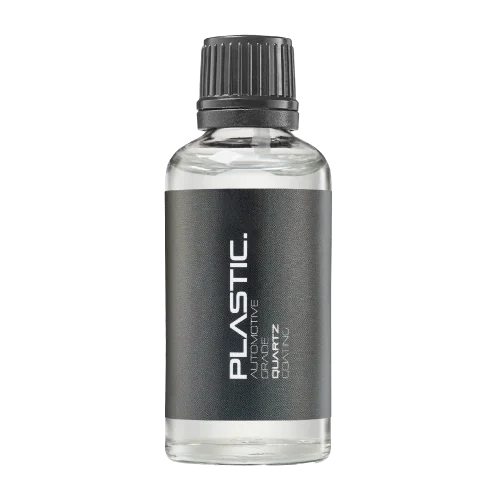 TRIM PROTECTIONPLASTICProtection for plastic surfaces.Discover
Dedicated care for the surfaces inside.
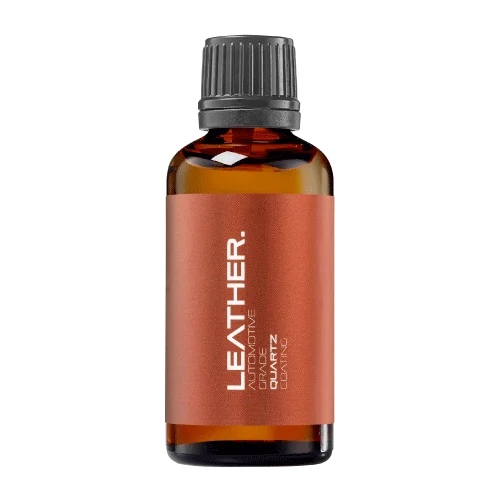 LEATHER SURFACESLEATHERDiscover NANOLAB leather protection.Discover PLASTIC SURFACESPLASTICProtection for interior plastic surfaces.Discover TEXTILE SURFACESFABRICExplore the latest fabric formulation.Discover
Spray protection, maintenance and upcoming wash products.
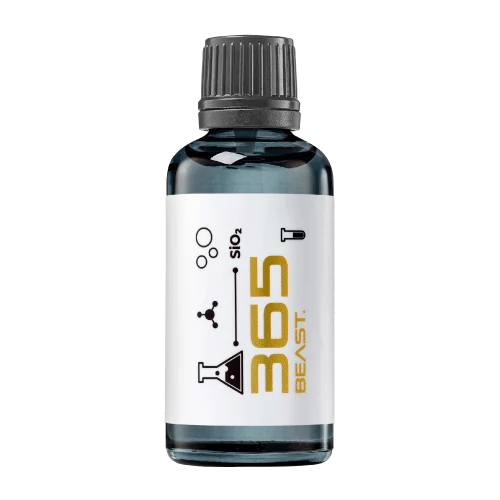 MAINTENANCEBEAST 365Explore the BEAST maintenance range.Discover
Next in washing, cleaning & care.
Ceramic protection for boats and yachts.
An easy-to-apply ceramic coating with an established track record on boats and yachts around the world.
Results vary with surface preparation, exposure and maintenance.
Read 50 MARINE guides →Explore MARINEProtection for the surfaces you live with.
A look at what we’re developing.
From cutting and one-step correction to final finishing.
A wider range for professional vehicle care.
Taking shape alongside BEAST & MATRIX.
Practical guidance for your next coating project.
Explore all guides →
Removing a coating SKU does not necessarily remove every cost assigned to it. Before discontinuing a product on a spreadsheet result, identify which revenues and costs would actually change.
Updated · NANOLAB Knowledge
A product can carry allocated shared expenses that remain after it is removed. Conversely, it may create specific handling, support or stock costs that are genuinely avoidable. The decision needs a defined scenario, including the effect on related product sales and customer requirements, rather than a single allocated profit figure.
Illustrative example: a SKU appears unprofitable after receiving a share of warehouse rent, but the warehouse cost would remain unchanged if the SKU disappeared. That allocation alone does not establish the benefit of removal. The decision needs the actual incremental effects of the proposed change.
This example is an analytical distinction, not advice to retain every low-volume product. Stock condition, operational complexity and strategic fit still matter. Use appropriate business and accounting judgement, and avoid treating a cost allocation as proof of a future saving.
Discuss bulk supply and private-label requirements with NANOLAB. Use the current product documentation for formulation-specific instructions.
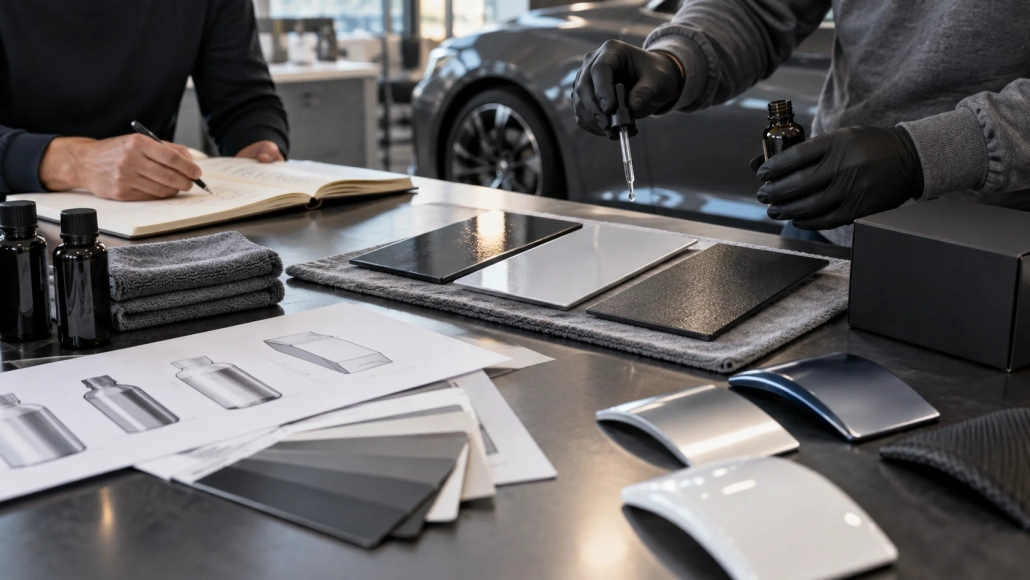
Assess missing customer tasks, surface compatibility and aftercare needs before adding another product to a private label coating range.
Specify consistent bottle scale, label legibility and variant identity for a coherent product catalogue.
A multi-product coating order can share packaging, handling and delivery costs. Allocate those costs consistently for product analysis while ensuring the whole-order calculation includes each cost only once.