A full polishing range.
From cutting and one-step correction to final finishing.
Specialist chemistry. Expert application.
 QUARTZ99 / CERAMIC BASE COAT
The foundation of your coating system.
A layerable quartz base coat designed for mechanical protection. Pair it with a suitable top coat to create the final finish.
For application by NANOLAB certified installers only.
Four formulas. Extended working time. Find the coating for your finish.
Explore the BEAST family of ceramic coatings.
Find the coating for each exterior surface.
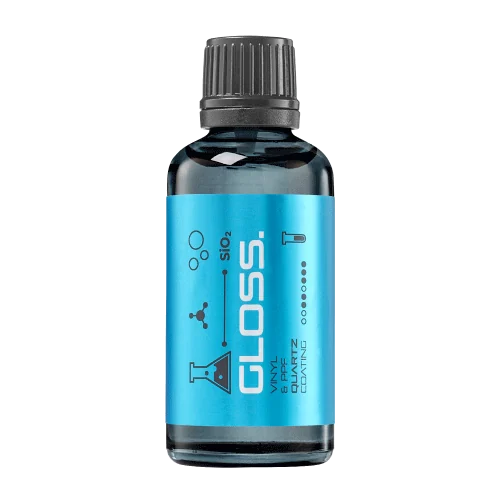 PPF & VINYLGLOSSProtection for glossy films and wraps.Discover
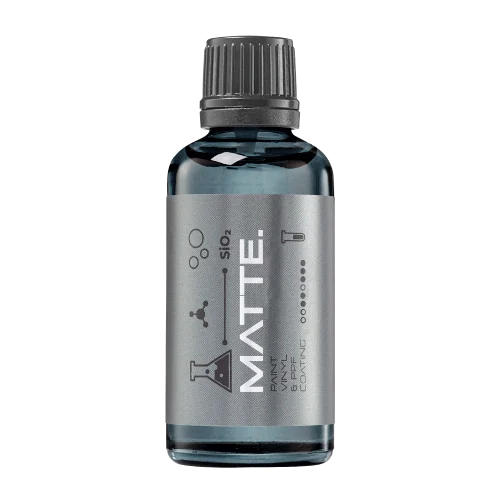 MATTE & SATINMATTEProtection that respects the finish.Discover
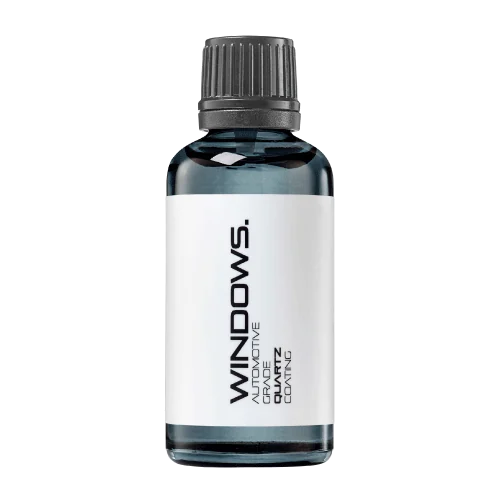 GLASSWINDOWSExplore dedicated glass protection.Discover
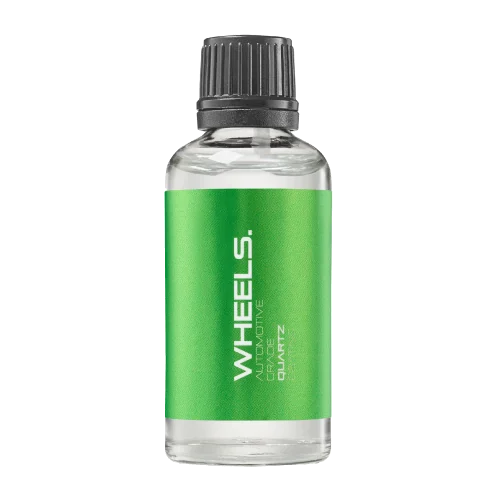 WHEEL PROTECTIONWHEELSA dedicated coating for your wheels.Discover
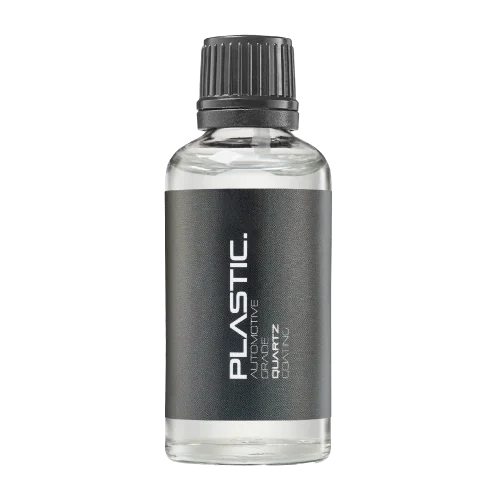 TRIM PROTECTIONPLASTICProtection for plastic surfaces.Discover
Dedicated care for the surfaces inside.
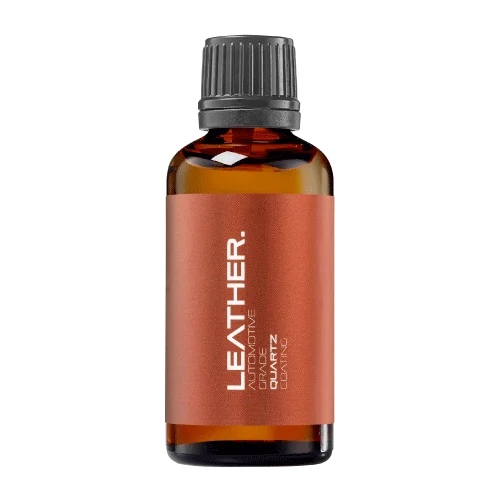 LEATHER SURFACESLEATHERDiscover NANOLAB leather protection.Discover PLASTIC SURFACESPLASTICProtection for interior plastic surfaces.Discover TEXTILE SURFACESFABRICExplore the latest fabric formulation.Discover
Spray protection, maintenance and upcoming wash products.
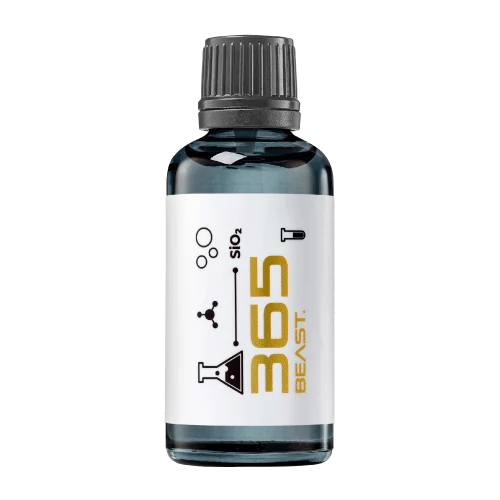 MAINTENANCEBEAST 365Explore the BEAST maintenance range.Discover
Next in washing, cleaning & care.
Ceramic protection for boats and yachts.
An easy-to-apply ceramic coating with an established track record on boats and yachts around the world.
Results vary with surface preparation, exposure and maintenance.
Read 50 MARINE guides →Explore MARINEProtection for the surfaces you live with.
A look at what we’re developing.
From cutting and one-step correction to final finishing.
A wider range for professional vehicle care.
Taking shape alongside BEAST & MATRIX.
Practical guidance for your next coating project.
Explore all guides →
Gross margin return on inventory relates gross margin to average inventory investment over a defined period. It can help compare stock commitments, but only when both quantities use consistent scope and clearly stated definitions.
Updated · NANOLAB Knowledge
A product with a strong unit margin may still tie up substantial inventory. Conversely, a fast-moving product with a smaller margin may use stock investment differently. The ratio does not replace cash-flow planning, availability targets or the costs excluded from gross margin, so keep those limitations visible in the review.
Arithmetic example: a hypothetical range generates 9,000 in gross margin with average inventory cost of 3,000. The ratio is three for the stated period. It does not mean the business earned three times its entire investment after every operating cost.
The figures are illustrative and are not a NANOLAB benchmark. Different accounting definitions can produce different results, so avoid comparing published ratios without checking their basis. Use this as one operational view of a coating range, not as a standalone investment recommendation.
Discuss bulk supply and private-label requirements with NANOLAB. Use the current product documentation for formulation-specific instructions.
Calculate markup and gross margin with the correct denominators and compare realistic private-label selling prices and cost bases.
Positive and negative forecast errors can cancel in an average while both cause operational problems. Preserve direction and magnitude.
Bottles allocated to approved sampling or demonstrations should remain distinguishable from ordinary saleable stock. Otherwise, an availability report can promise units that the business has already committed to another purpose.