A full polishing range.
From cutting and one-step correction to final finishing.
Specialist chemistry. Expert application.
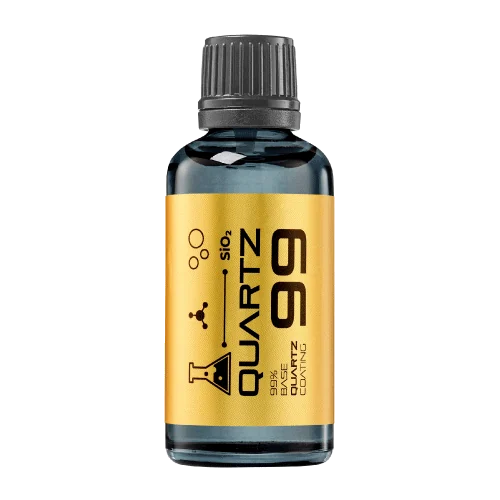 QUARTZ99 / CERAMIC BASE COAT
The foundation of your coating system.
A layerable quartz base coat designed for mechanical protection. Pair it with a suitable top coat to create the final finish.
For application by NANOLAB certified installers only.
Four formulas. Extended working time. Find the coating for your finish.
Explore the BEAST family of ceramic coatings.
Find the coating for each exterior surface.
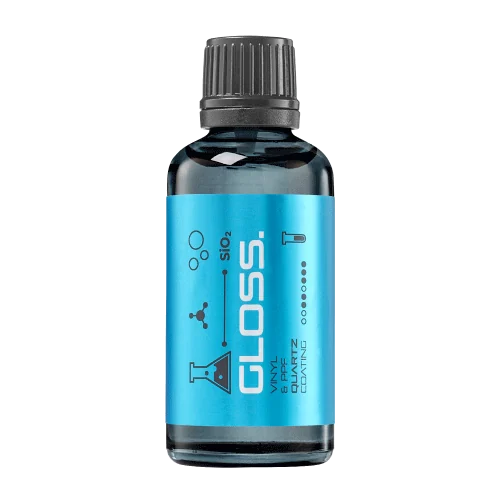 PPF & VINYLGLOSSProtection for glossy films and wraps.Discover
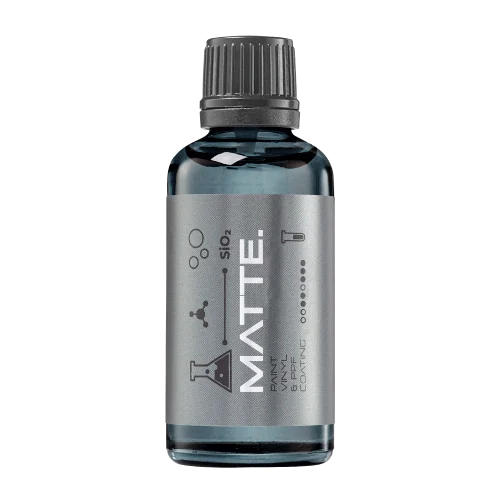 MATTE & SATINMATTEProtection that respects the finish.Discover
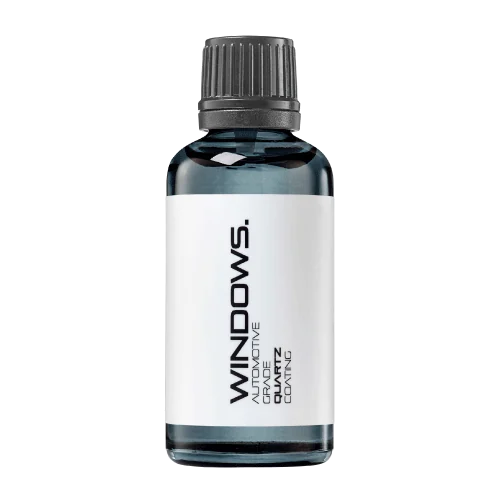 GLASSWINDOWSExplore dedicated glass protection.Discover
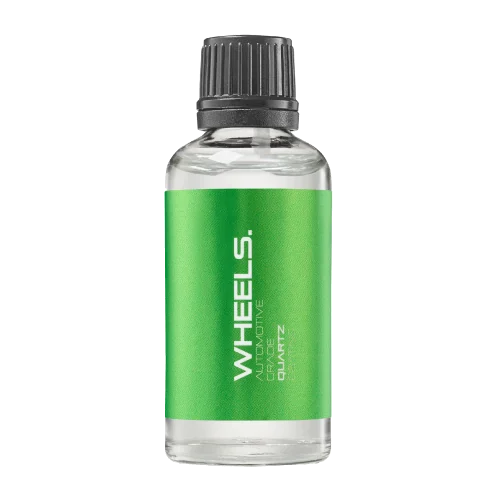 WHEEL PROTECTIONWHEELSA dedicated coating for your wheels.Discover
 TRIM PROTECTIONPLASTICProtection for plastic surfaces.Discover
Dedicated care for the surfaces inside.
 LEATHER SURFACESLEATHERDiscover NANOLAB leather protection.Discover PLASTIC SURFACESPLASTICProtection for interior plastic surfaces.Discover TEXTILE SURFACESFABRICExplore the latest fabric formulation.Discover
Spray protection, maintenance and upcoming wash products.
 MAINTENANCEBEAST 365Explore the BEAST maintenance range.Discover
Next in washing, cleaning & care.
Ceramic protection for boats and yachts.
An easy-to-apply ceramic coating with an established track record on boats and yachts around the world.
Results vary with surface preparation, exposure and maintenance.
Read 50 MARINE guides →Explore MARINEProtection for the surfaces you live with.
A look at what we’re developing.
From cutting and one-step correction to final finishing.
A wider range for professional vehicle care.
Taking shape alongside BEAST & MATRIX.
Practical guidance for your next coating project.
Explore all guides →
A launch breaks even on the costs included in the model when contribution covers those costs. Dividing setup cost by selling price ignores the variable cost of supplying each coating order and can understate the required sales volume.
Updated · NANOLAB Knowledge
Define contribution per unit as net selling revenue less the variable costs included in the analysis. Then divide the relevant fixed launch cost by that contribution and round up to whole saleable units. Keep the scope explicit: an initial launch-cost calculation is not automatically a complete business profitability forecast.
Arithmetic example: a hypothetical launch has 2,400 in setup costs and contribution of 12 per bottle. Recovering that setup cost requires 200 bottles. Dividing by a selling price of 30 would incorrectly suggest 80 bottles because it ignores the variable cost attached to each sale.
These numbers are illustrative, not NANOLAB prices or a profit promise. If contribution changes with volume, model the relevant ranges separately. Include additional operating costs when the question concerns overall profitability rather than recovery of a defined launch investment.
Discuss bulk supply and private-label requirements with NANOLAB. Use the current product documentation for formulation-specific instructions.
Calculate refill-packaging cost break-even using approved reuse procedures, actual cycles, labour and product losses.
Account for stockout periods when forecasting coating demand, distinguishing unobserved interest, delayed orders and actual sales.
A bundle should be evaluated using the revenue and costs of the complete basket. A profitable headline coating can conceal a weak offer if accessories, fulfilment or included aftercare products are omitted from the calculation.